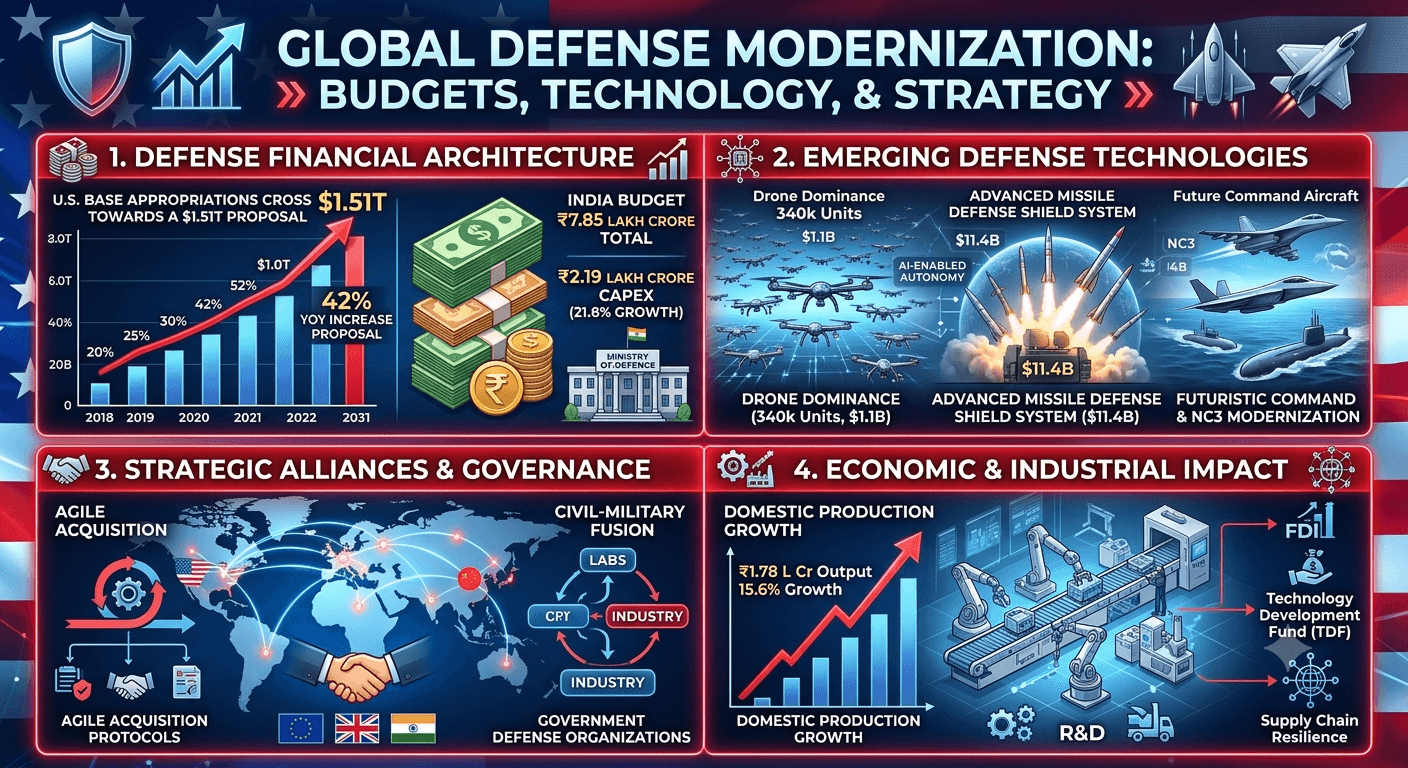
The November Week 1 edition of the BONC Network Newsletter provides a comprehensive global and Indian business outlook, highlighting key economic trends, market volatilities, and strategic opportunities. The primary themes dominating the global landscape include escalating oil prices due to the ongoing Iran war, a hawkish US Federal Reserve balancing inflation and rate expectations, record-high US bond yields, a market correction in Big Tech AI stocks, and slowing global GDP growth forecasts. On the domestic front, India navigates macro headwinds through resilient industrial activity, strong tax collections, and robust capital markets, alongside strategic policy shifts and upcoming key watch-events for businesses.
Key Section Summaries
1. Global Developments & Macro Trends
Oil Markets & Iran Conflict: The US-Israel conflict with Iran drove Brent crude to a high of around $113.10–$114+ in October (up 13.6% for the month) before settling at $109.98 on November 2. This volatility significantly impacts global inflation, central bank policies, and India's import bills (with India importing over 88% of its crude).
US Federal Reserve Policy: The Fed held rates at 3.75%–4.00% on October 28 following a 25 bps hike in September. With persistent inflation (CPI at 3.7% YoY) and rare dissenting votes, markets have priced in roughly an 85% probability of a December rate hike.
US Bond Yields: The 10-year US Treasury yield peaked near 5.36% in early October and hovered around 5.01% by late October, pushing the 30-year mortgage rate to approximately 7.24% and tightening global borrowing costs.
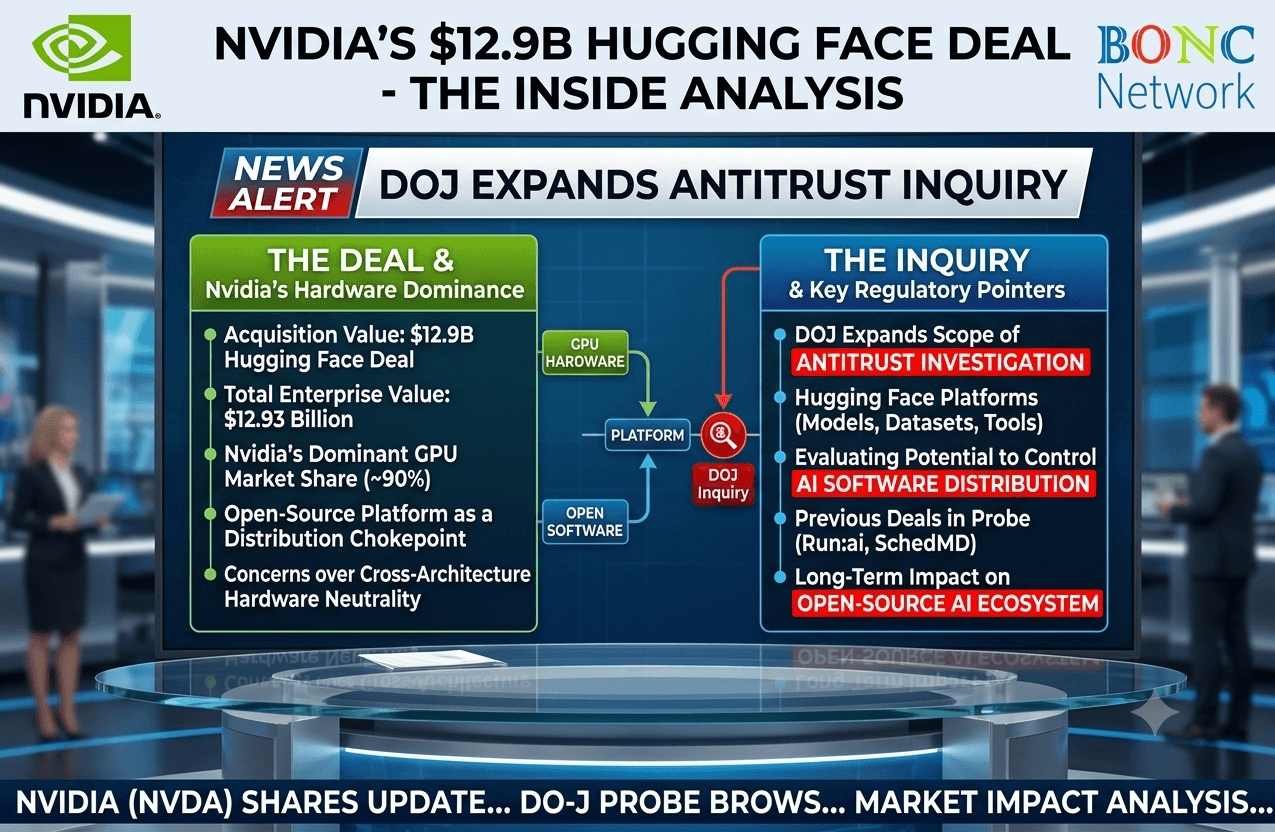
AI Stock Correction & Tech Spending: High-flying AI tech stocks faced a significant correction in late October. The Nasdaq dropped 7.8% from its record highs, and Big Tech companies faced scrutiny over massive AI capital spending (e.g., Meta raising 2026 capex to $135–$145 billion) yielding negative free cash flows for several giants.
Global Economic Growth: UNCTAD and the IMF project global GDP growth to slow down from 3.5% in 2025 to 3.1% in 2026, driven by geopolitical tensions, energy disruptions, and tightening financial conditions.
2. Financial Markets & Asset Updates
Equities: US markets experienced volatility with the S&P 500 closing around 7,663 in late October, while India's Sensex gained 2.73% in October to close at 74,459.53 (and Nifty rising 1.91% to 23,053.10).
Commodities & Currencies: Gold hovered around $4,005 on October 30 under rate-hike pressures, Bitcoin dipped below $80,000 in late October, and the Indian Rupee fluctuated between ₹94.9 and ₹96.9 per USD alongside foreign capital outflows of ₹3.08 trillion from Indian equities in 2026.
3. India Business & Policy Updates
Monetary & Fiscal Position: The Reserve Bank of India (RBI) raised its repo rate by 25 bps to 5.50% (its first hike since Feb 2023). India's CPI inflation stands at 5.54% and WPI at 11.39%. Meanwhile, GST collections rose 14.7% YoY to ₹2.03 lakh crore in September.
Capital Markets & Startups: IPO activity surged, led by Jio Platforms' ₹30,213-crore issue, contributing to a total of ₹44,451 crore in mainboard IPOs in October. Startup funding reached $2.2 billion in Q3 (up 5% YoY), with AI startups surging 265% to $438 million.
Trade & External Policies: Upcoming trade milestones include the India-EU FTA targeted before the end of 2026, alongside ongoing management of US tariff regimes and the Carbon Border Adjustment Mechanism (CBAM).
4. Strategic Market Outlook
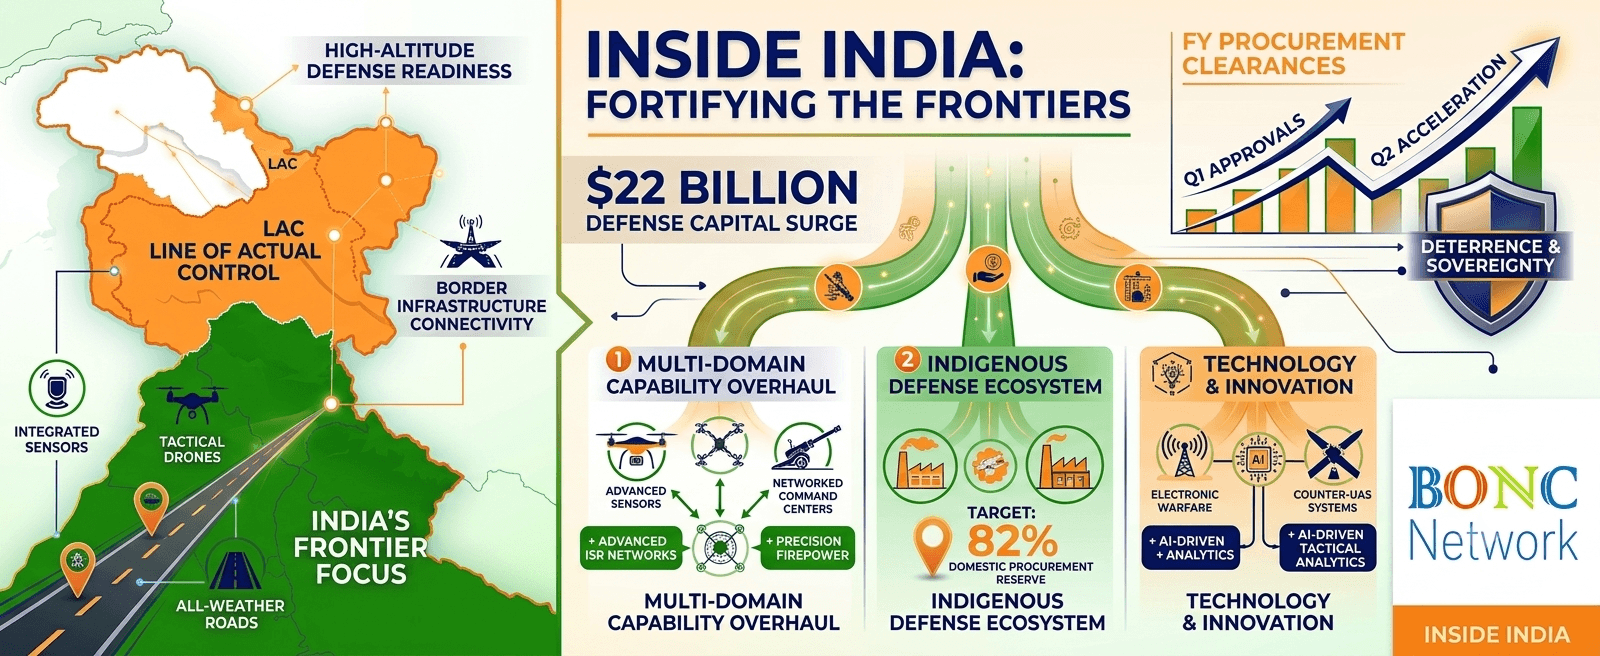
Growth Sectors: Domestic demand & manufacturing, defence & electronics, power & renewables, IT services, capital markets, upstream oil & gas, and AI startups.
Vulnerable Sectors: Oil marketing companies & airlines, crude derivatives, rate-sensitive sectors, unhedged dollar debt, steel & aluminium exporters, food processors, and late-stage startups.
Key Events to Watch: US midterm elections (Nov 3), India's October CPI (Nov 12), the Fed meeting (Dec 9), RBI policy, and the Union Budget 2027.
As the global economy navigates the crosscurrents of shifting central bank policies, energy volatility, and high-stakes technological evolution, agility and foresight remain your greatest competitive advantages. Whether you are managing risk in rate-sensitive sectors, capitalizing on India's robust domestic momentum, or monitoring the shifting dynamics of Big Tech and AI, staying informed is the key to staying ahead.
Thank you for reading the BONC Network Newsletter. We invite you to share your insights, discussions, and updates by " BONC it " on the platform.
Stay informed. Stay ahead.
November, 3rd, 2026
Team BONC Network