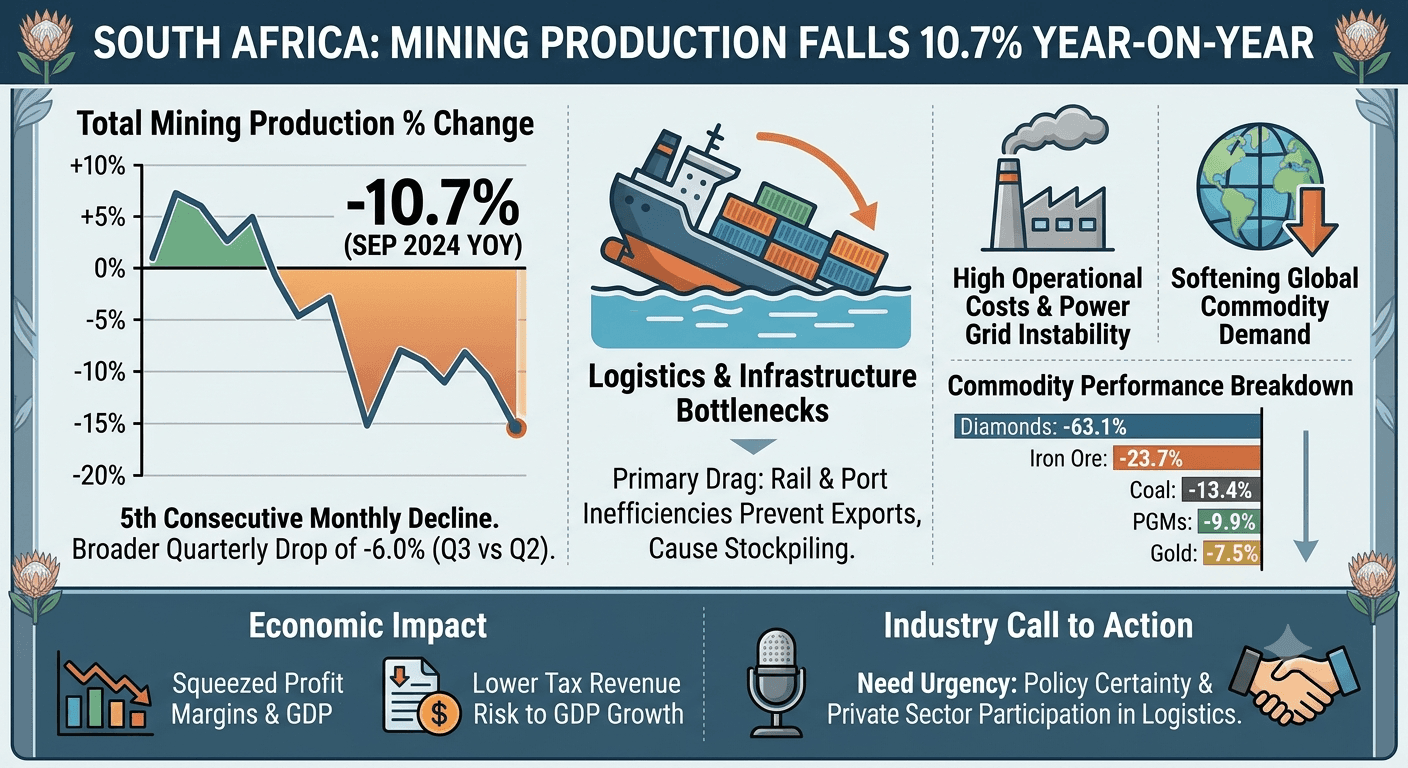
South Africa’s mining industry recorded a sharp 10.7% year-on-year drop in production, marking its fifth consecutive monthly decline and one of the steepest single-month contractions since late 2022.
The figures highlight deep structural issues—such as freight rail disruptions, port congestion, and escalating power costs—alongside softening global commodity demand. Total mineral sales at current prices also fell 4.1% year-on-year, reflecting pressure on both production volumes and market realisations.
South African Mining Production (Key Statistics)
Year-on-Year Production Growth │ -10.7%
Quarterly Production Decline (Q3 vs Q2) │ -6.0%
Year-on-Year Mineral Sales Drop │ -4.1%
Month-on-Month Rebound (Sep vs Aug) │ +2.8%
Commodity Breakdown: Winners & Losers
The contraction hit 10 out of 12 mining sub-sectors, with industrial and precious metals taking the heaviest blows.
Diamonds: Surged downward with a 63.1% decline year-on-year as reduced global consumer demand and synthetic diamond competition pressured rough stone markets.
Iron Ore: Production dropped 23.7%, driven by severe logistics bottlenecks on Transnet’s export rail corridors.
Coal: Output contracted by 13.4%, impacted by supply-chain limits and shifting global energy demand.
Platinum Group Metals (PGMs): Fell 9.9% year-on-year. PGMs remain the single largest structural drag on quarterly performance, reducing overall mining sector output by 3.5 percentage points during the quarter.
Gold: Decreased 7.5%, continuing a long-term decline in output due to deep-level mining challenges and lower ore grades.
Building Materials & Other Metals: Fell 12.5% and 11.6% respectively.
The Outliers
Chromium Ore: Rose 13.1% year-on-year.
Manganese Ore: Gained 12.8% year-on-year.
Both minerals benefited from sustained demand in global ferroalloy and steel production markets. On a month-on-month basis, seasonally adjusted mining output saw a 2.8% increase in September compared to August, providing modest short-term relief despite broader quarterly contraction.
Economic Implications & Industry Challenges
The sustained slump in mining output directly threatens South Africa's macroeconomic performance:
GDP & Fiscal Pressures: Mining directly generates ~6% of South Africa's nominal GDP and accounts for over 14% of corporate tax receipts. A 6.0% quarterly decline in Q3 production threatens third-quarter growth figures and government revenue collections.
Logistics Bottlenecks: State infrastructure challenges—specifically inefficiencies in Transnet's freight rail lines and port operations—prevent miners from moving mined stock to ports, resulting in stockpiling and reduced output.
Operational Cost Burden: Rising electricity tariffs from Eskom, alongside deep-level operational complexities, continue to squeeze profit margins across major producers.
Industry bodies, including the Junior Mining Council (JMC) and the Minerals Council South Africa, continue to call for urgent policy certainty, expedited private sector participation in logistics infrastructure, and streamlined regulatory approvals to attract foreign direct investment.